Perspectives

Where the rubber hits the road: Real-world uses cases of real-time payments

This article was originally published in the 2026 Canadian Payment Methods and Trends (CPMT) Report.

Authors
Image
Stephen Yun headshot

Stephen Yun

Senior Analyst, Product and Market Research, Payments Canada

Stephen Yun is a Senior Research Analyst at Payments Canada, whose areas of focus include the Consumer Payment Methods and Trends and Payment Behaviour Tracking studies, and leveraging research insights to create a consumer/business payment narrative and drive business action for his business partners.
 

Image
Headshot of Sanjay Sharma

Sanjay Sharma

Analyst, Strategic Foresight, Payments Canada

Sanjay Sharma is a Strategic Foresight Analyst at Payments Canada. He has extensive experience in the Canadian financial services industry in market intelligence, investor relations, trend research and content development with companies such as Mintel, the Government of Ontario, Ipsos and the Canadian Securities Institute.


Real-time payments are transforming the global financial landscape, whether it be through advancing greater financial inclusion, redefining cross-border trade and remittances, or shifting corporate treasury to "just-in-time" finance. Real-time payment systems provide the foundational infrastructure to foster more innovation, competition, efficiency and connectivity within the global economy. Working with our financial institution members, regulators and stakeholder partners, Payments Canada is transforming Canada's payment platforms to ensure it remains globally competitive in today’s digital economy. The RTR, launching in Q4 of 2026, is Canada’s new real-time exchange and clearing and settlement payment system that supports instant, data-rich payments. It will enable Canadians to conduct payment transactions in real-time. This article explores how the benefits of real-time payments will have an impact on end users in the form of real-world use cases. It identifies some of the more promising use cases and how they can benefit the daily lives of Canadians and/or the day-to-day operations of businesses.

What are real-time payments?

Real-time payments are electronic payments made between bank accounts that are initiated, cleared and settled within seconds, at any time of the day or week, holidays and weekends included.

Today, consumers and businesses have access to a wide variety of payment methods, including credit, debit and prepaid cards, Interac e-Transfer, electronic funds transfer, wires, cheques and cash. Unlike these current methods, real-time payments will allow them to move their money much faster and more securely, with finality of settlement. Being able to send and receive a payment instantly allows consumers and businesses to avoid potential late fees and better predict when they will get paid. Since payments are sent, cleared and settled in seconds, they will know their funds have been deposited securely with no risk of cancellation. Real-time payments also use the ISO 20022 financial messaging standard which allows payment messages to carry more than just transaction amounts and account numbers. With ISO 20022, additional payment details can be embedded like invoice references, purchase order numbers, tax IDs and even full remittance details – such as who sent the funds and why – all in a machine-readable, structured format. For businesses and the government, this means fewer errors and faster payment reconciliation leading to greater operational efficiency.

Over 120 countries worldwide currently provide a form of real-time payments, with Canada introducing a single system to make the real-time exchange and settlement of payments happen.1 Real-time payments have the potential to transform Canada’s economy, giving Canadians more transparency and confidence in payments, helping them manage their money and providing access to their payments any day, any time.
What is the Real-Time Rail?

Canada’s Real-Time Rail (RTR) payment system, owned and operated by Payments Canada, is new national payment infrastructure that will allow Canadians to send and receive data-rich payments in real-time. These payments will not only be sent and received in real-time, but they will also clear and settle between their financial institutions in real-time, 24/7, 365 days a year.2

The RTR will transform Canada’s payment ecosystem by offering consumers and businesses the ability to send or receive payments instantly, anytime and without any risk that the payment might be reversed at a later time. Canada will also be among the first to launch a real-time payment system incorporating centralized fraud services such as fraud scoring, real-time risk monitoring and confirmation of payee checks from day one, which will enhance security.3

The journey to the RTR has been a complex undertaking and the goal of a resilient, high-performing and secure real-time solution is closer than ever. Testing of the RTR began after successful completion of the technical application build in Q3 of 2025. Testing occurs in multiple phases and includes, but is not limited to, system integration testing, user acceptance testing, industry assurance testing, operational readiness testing, performance testing and security testing. The comprehensive testing phase of Canada’s RTR ensures we are delivering an instant, reliable and resilient payment system that serves those in Canada well into the future.4

Canada’s RTR will launch following robust and successful testing that meets Canada’s expectations for a trusted and secure payment system. Overall, the ability to send or receive payments in real-time will give consumers greater certainty in transactions, increased transparency and greater control over their finances.

Consumer and business sentiment towards real-time payments

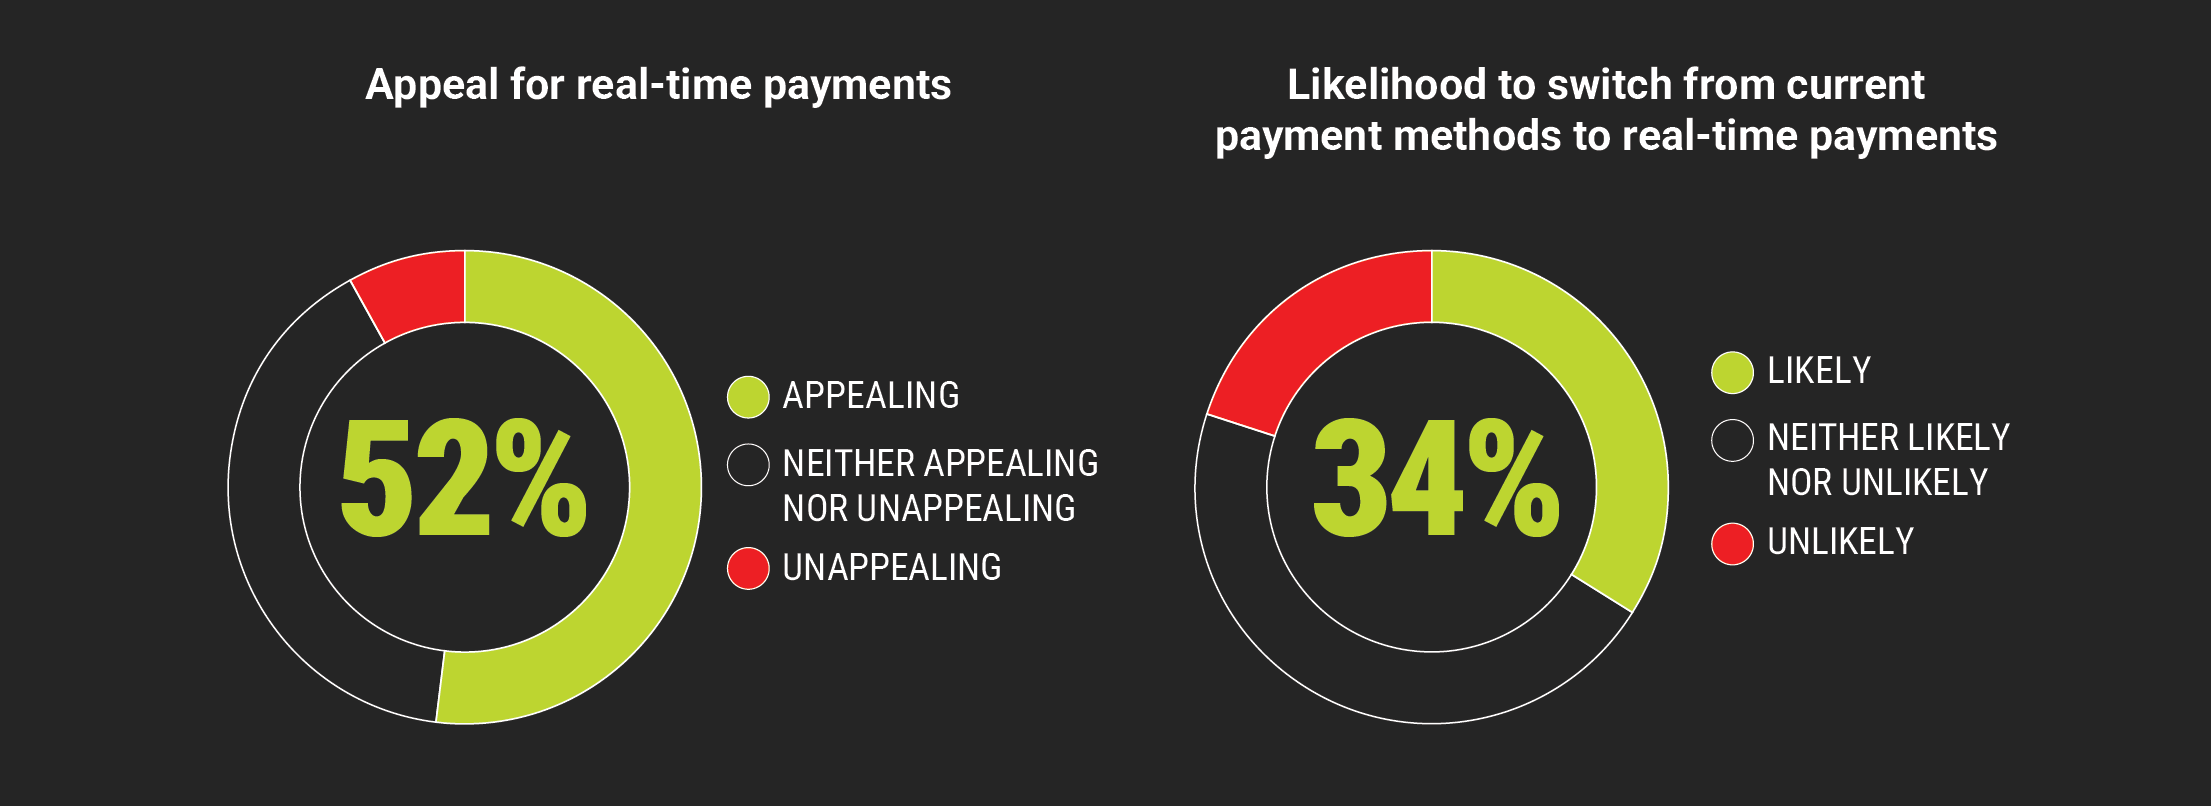
Payments Canada research indicates that many Canadians find real-time payments appealing. When asked about the appeal of real-time payments, over half of all Canadians (52 per cent) found it appealing, 40 per cent were neutral and only seven per cent found it not appealing. Furthermore, over one-third (34 per cent) would likely switch from their current payment methods to real-time payments.5 For more, see Figure 2: Consumer appeal and likelihood to switch to real-time payments. 

Figure 2 displaying consumer appeal and likelihood to switch to real-time payments, showing 52 per cent of consumers find real-time payments appealing and 34 per cent are likely to switch from current payment methods.
Figure 2: Consumer appeal and likelihood to switch to real-time payments. 

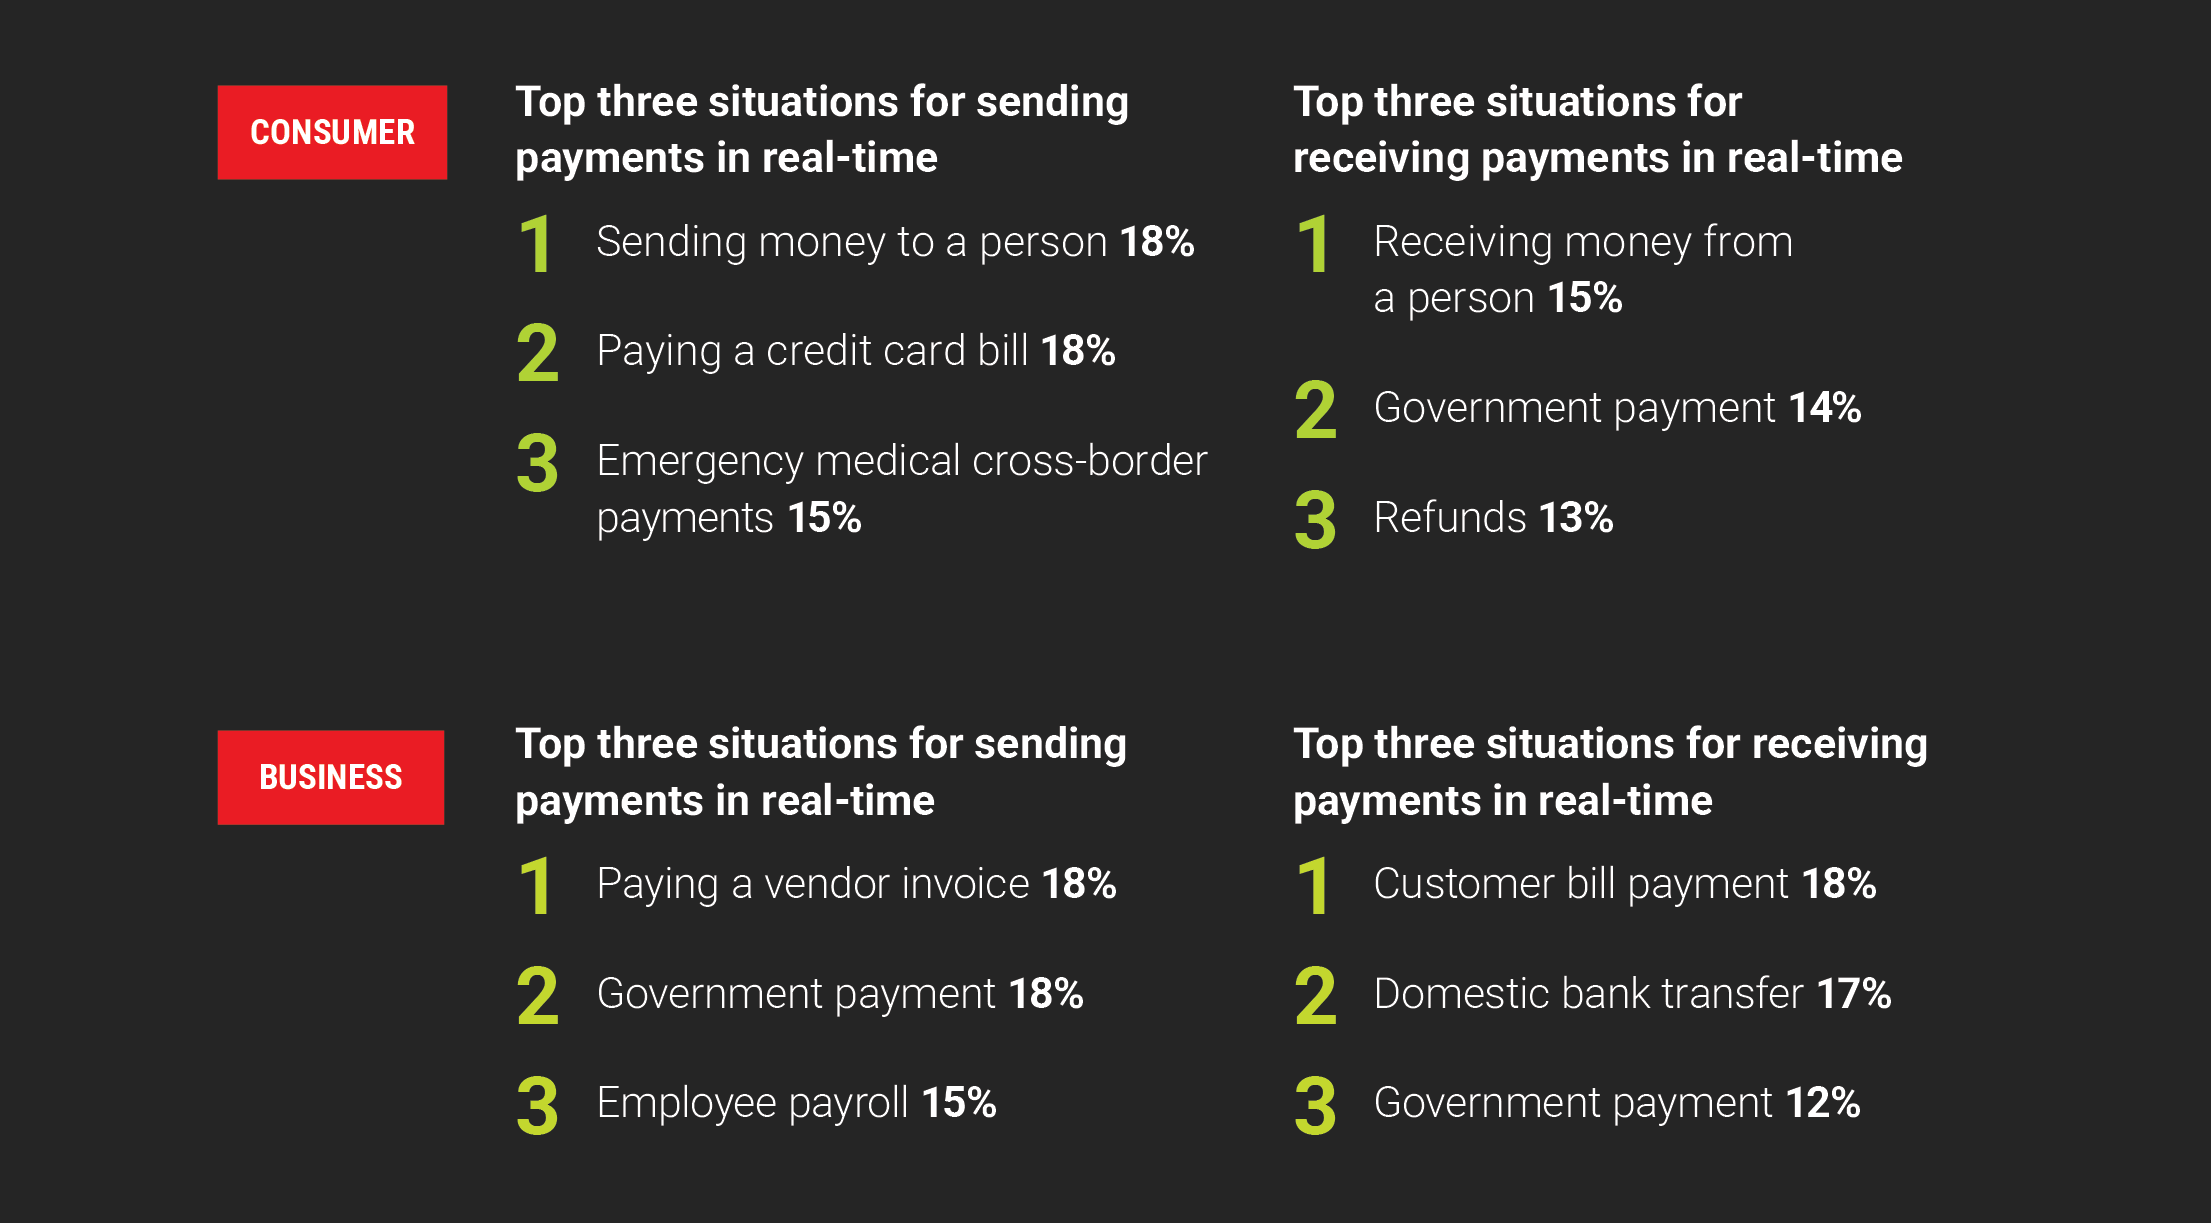
Consumers and businesses are interested in using real-time payments for a number of payment situations. The main use cases include peer-to-peer transfers, bill payments, government disbursements and paying vendors and employees.6 For more, see Figure 3: Top 3 situations for sending and receiving payments in real-time (consumer and business).

Figure 3 displaying the top three situations for sending and receiving real-time payments for consumers and businesses, highlighting top uses such as sending money to a person (18 per cent), paying vendor invoices (18 per cent) and customer bill payments (18 per cent).
Figure 3: Top 3 situations for sending and receiving payments in real-time (consumer and business).

The primary motivation for Canadians wanting to switch to real-time payments is the ability to send or receive payments faster than current payment methods allow — 29 per cent mentioned this as their main reason.7 Among those who are unlikely to switch to real-time payments for either making point-of-sale or remote payments, the main reason is that they are more comfortable using their current payment methods (32 per cent).8 In 2025, 63 per cent of Canadians reported not experiencing any type of payment challenges in a given six month period. However, almost one in four Canadians (24 per cent) were dissatisfied with the cost of payments.9 This result suggests that Canadians may choose to use a combination of real-time and current payment methods, depending on the situation, or keep using their current payment methods. This may change over time due to a better end-user understanding of real-time payments and their potential use cases.

Businesses rely on a variety of payment methods such as EFT, online bill payments, pre-authorized debit, Interac e-Transfer, credit card, cheques and wires for their operations. These are used for bill payments, paying suppliers and employees and receiving payments from customers and the government.

Payments Canada research showed that businesses were more likely than consumers to have experienced challenges when sending or receiving payments. In 2025, 39 per cent of businesses reported not experiencing any type of payment challenges in a given six month period (compared to 63 per cent for consumers).10 The main payment frustrations facing businesses in 2025 were: high fees (16 per cent); ensuring bills were paid on time (13 per cent); managing the business’ cash flow (11 per cent); processing delays (nine per cent); and security/safety (nine per cent).11 The features and benefits of the RTR address many of these payment pain points. As such, businesses may be more likely than consumers to switch from their current payment methods to real-time payments should that option be available. 
Important will be communications and outreach to businesses to confirm that sending/receiving payments in real-time is safe, secure, and from a cost perspective comparable or better than current payment methods.

Promising use cases for real-time payments

Real-time payments appeal to the majority of Canadians mainly for the speed and convenience they offer. Adoption of real-time payments by consumers and businesses is expected to be driven by specific use case characteristics where immediacy directly affects outcomes, particularly in disbursement scenarios. Several high-volume use case categories, such as bill payments and government receivables, are already well served by existing batch and scheduled payment methods (e.g., electronic funds transfer, debit and Interac e-Transfer). Real-time payments do not address a fundamental gap, but instead offer incremental improvements in data, speed, confirmation and control. There are stronger use cases where immediacy improves outcomes, and their adoption will largely depend on integration and operational readiness.

Gig worker payout

In Canada, nearly 4.6 million adults participate in the gig economy, working as freelancers or temporary contract workers. It includes individuals who use online gig platforms in which they may connect with clients through online platforms or apps, or take on gig/temporary work, or through more traditional methods such as going through a temporary worker staffing agency, through word-of-mouth referrals and professional networking.12 Gig worker payout represents a strong use case for real-time payments, which would provide valuable benefits to both the payor (business) and payee (gig worker).

The most common ways in which gig workers get paid in Canada are via EFT direct deposit, Interac e-Transfer, cheque, PayPal transfer and cash. Both businesses and gig workers currently prefer using Interac e-Transfer and EFT direct deposit for the convenience and security. Cheque is also currently preferred by businesses for paying gig workers, partly because it makes payment reconciliation easier. Cash is another preferred option by gig workers for getting paid because it allows them to be paid instantly.13

For businesses that hire gig workers, the top payment irritants they encounter when paying gig workers are: payment reconciliation (34 per cent); the time it takes for gig workers to receive their pay once their contract is over (27 per cent); traceability of the payments (21 per cent); and the fees associated with the payment methods used (14 per cent).14

For gig workers, the top payment irritants they encounter when receiving payment for their services after completing their job or contract are: the time it takes to get paid once a contract is over (36 per cent); the fees associated with the payment method used by the employer (25 per cent); and getting paid by cheque (20 per cent).15

Regarding fees, financial institutions charge users a range of fees associated with different payment methods. Fee exposure varies by payment method and institution; certain methods (e.g., push-to-card, wire, cheque) may carry higher direct or indirect costs.

For these reasons, both the payor (business) and payee (gig worker) within the gig worker payout scenario might have a low to medium attachment with their existing payment solution and be open to adopting new solutions that address their payment frictions.

The key benefits of real-time payments for businesses for this use case are: instant, 24/7 payment; data-rich payments (i.e., structured remittance data enabling automated reconciliation and clearer payment references); and more efficient and scalable disbursement compared to existing methods (e.g., Interac e-Transfer limits, batch constraints and administrative overhead when paying multiple workers). Similarly, the key benefits of real-time payments for gig workers for this use case are: instant, 24/7 access to earnings; reduced reliance on delayed or fragmented payment methods (e.g., waiting for batch deposits or dealing with multiple Interac e-Transfer payments due to amount limits); and lower exposure to fees or workaround costs associated with accessing funds (e.g., avoiding payday loans due to faster payout timing).

These benefits are not theoretical. Across international jurisdictions with live real-time payment systems, contractor and worker payouts have emerged as a successful early adoption use case. In Brazil, food delivery drivers, rideshare workers and micro-entrepreneurs rely heavily on Pix, the country’s instant payment system. It has become the gold standard for instant payouts in Latin America, virtually replacing cash and traditional debit transfers for the gig workforce.16 In India, logistics, food delivery (like Zomato and Swiggy) and rideshare platforms use United Payments Interface (UPI) to push earnings directly into workers' bank accounts or digital wallets immediately after a task is completed. It is highly cost-effective for platforms as it bypasses traditional card processing fees.17 The UK has millions of individuals participating in the gig economy. Courier, courier-delivery and freelance platforms utilize Faster Payment System (FPS) to clear sterling payments into worker bank accounts within seconds, keeping driver turnover low.18 And, in the US, real-time and near-real-time rails are widely used for gig and contractor payouts.

In Canada, the success of this use case would depend on: financial institution readiness to originate real-time disbursements; employer operational adjustments to payout timing; employer technical upgrades to their Enterprise Resource Planning system; fraud and liquidity controls; and business incentive relative to current payment methods. Importantly, Canada's RTR will be among the first to include centralized fraud services, such as confirmation of payee, from day one. This ensures that businesses and individuals can benefit from instant wage payouts while having the right guardrails in place to protect them.

Insurance claims payout

The RTR can enable insurance providers to push claim payouts to policyholders’ accounts seconds after approval. Funds can be immediately accessed in emergency scenarios (e.g., house fires or accidents) where victims require immediate liquidity (e.g. for temporary housing or repairs). Instant payment for insurance claim payouts can benefit both consumers (B2C payments) and commercial businesses (B2B payments).

For insurance providers, delays in customer claim settlement lead to overall customer dissatisfaction and are the biggest driver of customer churn. For customers, claim settlement time is the biggest pain point. Research released in 2025 indicates that individuals who receive disbursements (like insurance claims) instantly report up to 17 per cent higher satisfaction than those waiting for traditional methods like cheques or delayed EFTs.19 The latest Ipsos data on the Canadian insurance sector identifies "payment clarity" and "real-time status" as the two biggest friction points. The report suggests that removing friction from claims — specifically through immediate resolution and payment — is the fastest way to build trust.20

Modern policyholders expect the same frictionless financial interactions they get from dealing with platform-based technology companies or fintechs (e.g., Uber, SkipTheDishes, KOHO or Wealthsimple). The shift toward real-time insurance payouts is part of a broader movement in fintech toward embedded finance, where disbursements are seamless, user-controlled and increasingly invisible. For these reasons, both insurance providers and their customers might be open to new solutions for sending and receiving an insurance claim payout.

The key benefits of real-time payments for insurance providers would be: instant, 24/7, data-rich payments; potentially lower overall cost and greater efficiency relative to cheques and wires; and improving customer satisfaction and loyalty. The key benefit of real-time payments to claimants is faster access to funds, especially during time-sensitive situations like emergencies.

The Asia-Pacific region leads the world in real-time insurance claim disbursements, heavily supported by government-backed infrastructure and mobile-first consumer habits. In India, insurtechs and traditional insurers heavily leverage the UPI to send instant health, auto and crop insurance payouts directly to bank accounts or digital wallets via mobile numbers or virtual payment addresses.21 Singapore (PayNow) and Thailand (PromptPay) operate well-established real-time networks that are interconnected. Insurers use them for near-instant travel and health insurance claims.22 Through PayID, Australian insurers widely offer real-time claims payouts to customers' bank accounts, cutting out the traditional two- to three-day bank processing wait.23 In other jurisdictions such as the UK, US and Brazil, real-time rails have been used to enable faster insurance claim payments where insurers integrate real-time payments capabilities into their claims systems.

Several things would need to be in place for instant insurance claim disbursements to take hold in Canada. Most importantly, insurance providers need to integrate their claims management system into a financial institution’s APIs that route to the RTR for payment initiation. To this end, the insurance provider needs to be operationally ready to originate real-time payments. To safely and effectively start initiating instant claim disbursements, the insurance provider must address operational pillars such as upgrading their fraud detection abilities, shifting from batch to continuous reconciliation and revamping their liquidity and cash management strategy. Other key factors include: the ability for receiving financial institutions to accept RTR payments; and the availability of accurate recipient payment credentials.

Overall, insurance claims payout represents a strong disbursement use case where immediacy directly improves customer experience and financial recovery following insured losses. Value is particularly high in time-sensitive or high-impact claims, while broader adoption depends on insurer integration with claims processing and payment systems. This use case includes both consumer (B2C) and commercial (B2B) insurance payouts, expanding applicability, but introduces additional operational complexity.

Instant supplier payment

Instant supplier payment is another strong use case where real-time payments can benefit both the payor (business) and payee (supplier/vendor). This use case focuses on B2B payments involving businesses that operate just-in-time (JIT) or near-JIT supply chains. JIT is a form of inventory management that requires working closely with suppliers so that raw materials arrive as production is scheduled to begin, but no sooner. The goal is to have the minimum amount of inventory on hand to meet demand.24

A common friction point facing businesses that operate JIT supply chains is that they are not able to have their shipments (such as raw materials, finished goods) released immediately until the payment to the supplier/vendor is settled. With current payment methods, this can take days, which means they are forced to wait longer for their shipment to arrive. For example, the majority of businesses use EFT for paying their suppliers. Pre-authorized debits are commonly used by businesses to pay for goods and services related to business activity (often recurring).25 Business pre-authorized debits generally take three to five business days to clear and settle through the batch payment system. Usually, funds are held for a set number of business days before being released to allow for standard returns such as non-sufficient funds, invalid account, closed account or stopped payment. As a result, this wait time negatively impacts production times, revenue generation and cash flow management. It requires businesses to maintain a float to ensure adequate funds are available to pay for purchases due to settlement delays. For the supplier/vendor, the delay in getting paid also negatively impacts revenue generation and cash flow management.

For these reasons, businesses that operate a JIT or near-JIT supply chain could benefit from more efficient payment methods. Payments Canada research indicates that 18 per cent of SMEs and 23 per cent of mid-market businesses would use real-time payments to pay a supplier/vendor. Also, 17 per cent of SMEs and 24 per cent of mid-market businesses indicated that they would use real-time payments to receive a customer bill payment (from a business client).26

Almost one in four businesses (SME: 23 per cent, mid-market: 24 per cent) indicated that the main concern they have about real-time payments is whether the cost of this service would be more than what they pay now for sending/receiving payments.27 An increase in fees is more likely to affect SMEs as they are highly sensitive to changes impacting their business costs. They would be faster to react to a change in fees versus mid-market businesses. Research conducted among SMEs uncovered that most businesses could manage a small increase in transaction fees (one to two per cent), but nearly all indicated that an increase beyond that would likely result in a change in payment type, or change in banking institution.28

The key benefits of real-time payments for both payor and payee for this use case are: instant, 24/7 payment; and potentially lower overall cost relative to higher-cost methods such as push-to-card, wires or cheques depending on pricing structure. However, the potential lower cost would not be a primary factor compared to existing low-cost options, such as Interac e-Transfer or business pre-authorized debits/pre-authorized credits. For the supplier/vendor, real-time payments also provide greater certainty of funds without any risk that the payment might be reversed at a later time.

The instant supplier payout use case can be observed in action in other jurisdictions where real-time payments are supported. For example, in the UK, FPS enables immediate business transfers.29 In Australia, NPP supports real-time transfers between business accounts.30 And, in Brazil, Pix allows businesses to transfer funds instantly to other businesses.31

For this use case to be realized successfully in Canada, the sending financial institutions must enable RTR payments from business accounts. Similarly, the receiving financial institutions must be able to receive and credit RTR payments to supplier accounts. Adoption also depends on integration with accounts payable systems, supplier invoicing workflows and appropriate fraud and liquidity controls.

Overall, instant supplier payment represents a strong operational use case where immediate settlement improves supplier liquidity and payment certainty. The value is highest in time-sensitive or JIT supply chain scenarios, but adoption depends on buyer payment behaviour, cost considerations and treasury practices. Continued reliance on scheduled payments for working capital management limits migration, potentially resulting in targeted rather than broad adoption. This implies the need to support competitive pricing, integration into treasury and accounts payable workflows and sufficient transaction limits and data capabilities to enable invoice-level reconciliation, in order to expand adoption beyond time-sensitive use cases.

Conclusion

This article explored several promising use cases of real-time payments. Other potential use cases of real-time payments include: consumer rent payments; immediate loan funding; domestic wire alternative; government disbursements; immediate merchant payouts and real estate transactions. The two factors that most likely will drive the creation and adoption of real-time payment use cases are: 1) it addresses an unmet need, or solves an existing problem; and 2) the dependencies that allow the use case to materialize are met. For this reason, some use cases of real-time payments will undoubtedly follow a quicker path to market than others.

Overall, RTR adoption is expected to be selective. The RTR will complement existing payment systems rather than broadly displacing them. Batch processes will remain central in areas where current efficiency, liquidity management and process integration outweigh the need for immediacy. The pace of adoption will be determined less by the availability of the rail and more by ecosystem readiness, including biller and government integration, workflow alignment and the potential development of supporting capabilities such as Request-to-Pay. The RTR will succeed where it is embedded into specific payment journeys with clear value, rather than as a general-purpose replacement for existing payment methods.

The impending launch of the RTR will modernize Canada's financial landscape by enabling data-rich electronic payments to clear and settle instantly, 24/7/365. For consumers, this means unprecedented control over their finances, allowing them to make time-sensitive payments and see the funds transfer in seconds. For businesses, the RTR will provide an immediate boost to liquidity and cash flow management, allowing them to make better business decisions, strengthen their operations and contribute to Canada’s economic prosperity. Finally, the RTR paves the way for payment service providers to build tailored, innovative financial products, offering consumers and businesses more choice in how they pay and get paid.


1 For more, see: The Real-Time Payments World Map | PYMNTS.com.

2 For more, see: Real-Time Rail payment system.

3 Fraud scoring is a method of assessing the likelihood of a transaction being fraudulent, assigning a numerical score based on various factors and data points. Real-time risk monitoring involves continuously analyzing financial transactions and customer behavior to detect and prevent fraudulent activities and other risks by assessing the risk level of each transaction based on current and historical data. Confirmation of payee is a payment verification service that confirms the account name matches the name you have entered for a payment.

4  For more, see: Real-Time Rail payment system.

5  Payments Canada/Leger. 2025 Consumer Payments Tracker Survey.

6  Payments Canada/Leger. 2025 Consumer and Business Payments Tracker Surveys.

7  Payments Canada/Leger. 2024 Consumer Payments Tracker Survey.

8 Ibid.

9 Ibid.

10 Payments Canada/Leger. 2025 Business Payments Tracker Survey.

11 Payments Canada/Leger. 2025 Business Payments Tracker Survey.

12 Payments Canada/Leger. 2026 Consumer Payments Tracker Survey.

13 Payments Canada/Leger. 2023 Consumer and Business Payments Tracker Surveys.

14 Payments Canada/Leger. 2023 Business Payments Tracker Survey.

15 Payments Canada/Leger. 2023 Consumer Payments Tracker Survey.

16 For more, see: Payment and Ecommerce Trends in Brazil for 2024 | PCMI.

17 For more, see: Fintech for Gig Platforms: Payments + Credit for Indian Drivers | Billcut.

18 For more, see: Real-time payouts for drivers and delivery workers - Fire.

19 For more, see: Instant Isn’t Optional: The Rise of Real-Time Payouts in Canada.

20 Ipsos. 2025 Canadian Satisfaction Index (CSI) Insurance Report.

21 For more, see: What Are Real-Time Payments? Worldwide Statistics | Thunes.

22 For more, see: The Ultimate Guide to Real-Time B2B Cross-Border Payments.

23 For more, see: Insurance Payments Platform | Monoova and What Is a PayID and How Does It Work? - Duck Creek.

24 For more, see: Just-in-Time (JIT) Inventory: A Definition and Comprehensive Guide | NetSuite.

25 Payments Canada/Leger. 2025 Business Payments Tracker Survey.

26 Ibid.

27 Payments Canada/Leger. 2025 Business Payments Tracker Survey.

28 Payments Canada/RSG. 2022 The Future of Retail Batch Payments in Canada Qualitative Research Report.

29 For more, see: What is Faster Payments? A guide to the UK's real-time bank transfer system.

30 For more, see: How Real Time Payments Are Transforming Business in Australia.

31 For more, see: A guide to Pix payments in Brazil | Stripe.

Keep reading